SPONSORED

Critical Minerals, Critical Countdown: 90 Days to Get It Right

A Temporary Tariff Thaw Unlocks Critical Minerals, but Can the U.S. Seize the Moment?
•• 2 Min
Critical Minerals, Critical Countdown: 90 Days to Get It Right

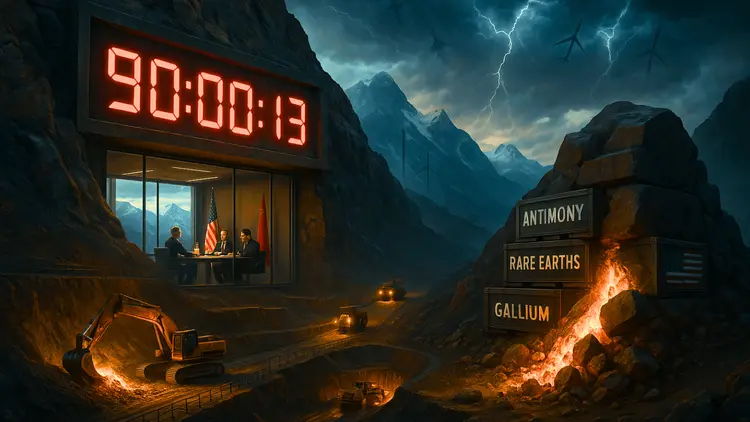
In a world where trade wars flare hotter than a steel furnace, the U.S. and China have decided to play nice—for 90 days, at least. Announced on May 12, 2025, after weekend talks in Geneva, this bilateral deal slashes tariffs and pries open China’s grip on critical minerals like antimony, rare earths, and gallium. It’s a diplomatic detente that’s got markets buzzing and miners dreaming, but don’t pop the champagne yet. This truce is a Band-Aid on a fractured supply chain, and for critical minerals—vital for everything from fighter jets to solar panels—the stakes are sky-high. Let’s unpack the deal, zoom in on the minerals that keep the world spinning, and ask: is this a game-changer or just a geopolitical timeout?

The Deal: Tariffs Down, Minerals Up

Picture this: U.S. Treasury Secretary Scott Bessent and Trade Representative Jamieson Greer squaring off with China’s Vice Premier He Lifeng in a Geneva conference room, hammering out a deal to cool the trade war’s latest inferno. The result? Starting May 14, 2025, tariffs on Chinese goods entering the U.S. drop from a jaw-dropping 145% to a still-hefty 30%, while U.S. goods heading to China see duties fall from 125% to 10% Fast Markets, May 13, 2025. But the real kicker for the mining crowd? China’s agreed to lift its export bans on critical minerals, imposed since April 2, 2025, which had choked off supplies of antimony, rare earths, and other high-tech essentials White House Joint Statement, May 12, 2025.

This isn’t just about numbers—it’s about survival. Critical minerals are the lifeblood of modern tech and defense. Rare earths power magnets in wind turbines and missiles; antimony hardens armor-piercing rounds; gallium keeps semiconductors humming. When China slammed the brakes on these exports in April 2024, prices skyrocketed—antimony alone hit $40,000 per ton, a 250% jump in a year Reuters, April 4, 2025. The U.S., which imports 63% of its antimony and 82% of its rare earths from China, felt the squeeze hard Bloomberg, April 16, 2025. This deal buys breathing room, but it’s a 90-day sprint, not a marathon victory.

Why Critical Minerals Are the Real Story

Let’s cut to the chase: critical minerals aren’t just rocks—they’re geopolitical chess pieces. China produces 48% of the world’s antimony and 90% of its rare earths, giving it a near-stranglehold on global supply TRENDS Research, February 11, 2025. When Beijing flexed its muscle with export bans in August and December 2024, U.S. defense contractors and clean energy firms scrambled. X users like @Artemisfornow were quick to sound the alarm: “China’s got us by the throat with antimony—80% of global supply. Time to mine our own!”

The trade deal’s promise to lift these restrictions is a win, but it’s not a free pass. The White House confirms China will “suspend or remove” its non-tariff barriers, including those pesky mineral bans Fast Markets, May 13, 2025. Yet, sectoral tariffs on autos, steel, and aluminum remain, and investigations into critical minerals tariffs are still simmering. Translation? The mineral market’s relief might be “muted,” as Fast Markets puts it, and the U.S. isn’t out of the woods.

The U.S. Response: Digging for Independence

The U.S. isn’t sitting on its hands. President Trump’s April 15, 2025, Executive Order launched a probe into the national security risks of imported critical minerals, signaling a push for self-reliance White House Fact Sheet, April 2025. On the ground, Perpetua Resources’ Stibnite Gold-Antimony Project in Idaho is a beacon of hope, with 148 million pounds of antimony reserves and $59.2 million in Defense Production Act funding. It could cover 35% of U.S. demand, but it’s years from full production. Meanwhile, the DOE’s $45 million investment in critical minerals consortia and U.S. Antimony Corporation’s Montana smelter expansion show the private sector’s waking up Mining Technology, January 14, 2025.

Allies are stepping up, too. Tajikistan, the world’s second-largest antimony producer, is cozying up via the C5+1 Critical Minerals Dialogue, while Australia’s nascent projects offer promise. But let’s be real: building mines and refineries takes time, and China’s Belt and Road Initiative is snapping up mineral assets from Indonesia to Africa AISI Statement, May 12, 2025. The U.S. needs to move faster than a startup chasing venture capital.

Market Buzz and Economic Jolt

Markets love a good truce. Share prices for auto and steel companies spiked, with the U.S. dollar and oil climbing while gold took a breather Reuters, May 12, 2025. Economists are downright giddy: UBS’s Jonathan Pingle predicts a 0.4% GDP boost for the U.S. this year, while J.P. Morgan upped China’s 2025 growth forecast to 4.8% Fast Markets, May 13, 2025. Businesses are exhaling, planning back-to-school imports with a bit more swagger, though 30% tariffs on Chinese goods still sting, as Oklahoma State’s Sunderesh Heragu notes.

For critical minerals, the deal’s a lifeline. Antimony miners, for instance, can breathe easier knowing China’s export ban is off the table—for now. But steel industry voices, like a distributor quoted by Fast Markets, warn that transshipping through Southeast Asia and Canada keeps Chinese influence alive. “A half-trillion trade deficit is too high,” they grumble, and they’re not wrong.

What’s Next? A 90-Day Countdown

This deal’s no fairy-tale ending. It’s a 90-day ceasefire, with high-level talks slated to continue between Bessent, Greer, and He Lifeng in the U.S., China, or a neutral third country Washington Post, May 12, 2025. The White House promises a “mechanism” for ongoing trade discussions, but details are scarcer than a domestic antimony mine. David Zervos of Jefferies sums up Trump’s style: “Big, destabilizing moves, then pull everyone back.” It’s classic brinkmanship, and it’s working—for now CNBC, May 12, 2025.

The risk? China’s got a playbook for weaponizing minerals, as seen in 2024’s bans. X user @TorstenProchnow put it bluntly: “China’s not playing nice forever. We need mines, not promises.” The U.S. must use this window to fast-track projects like Stibnite, streamline permitting, and lock in allied supplies. The Atlantic Council argues tariffs could secure mineral supply chains if targeted smartly Atlantic Council, April 18, 2025. Otherwise, when the 90 days are up, we’re back to square one.

The Bottom Line

The U.S.-China trade deal is a rare win in a world of tit-for-tat tariffs, putting critical minerals back on the table and giving industries a much-needed breather. But let’s not kid ourselves: 90 days is a blip, and China’s mineral muscle isn’t flexing any less. For antimony, rare earths, and gallium, the U.S. needs to dig deep—literally. From Idaho’s mountains to Tajikistan’s mines, the race is on to build a supply chain that doesn’t bow to Beijing. As Ahmad Assiri of Pepperstone quips, this is “a reverse Liberation Day”—not a fix, but a chance to pivot Fast Markets, May 13, 2025. So, miners, investors, and policymakers, grab your shovels. The clock’s ticking, and the stakes are critical.

Most Popular News

  1. SpaceX’s $8B Spectrum Deal Sends AT&T, Verizon, and T-Mobile Plummeting
  2. Is Project Vault Securing America’s Supply Chain or Squeezing It to the Breaking Point?
  3. Why Gautam Lohia Shifted from Global Consulting to Reboot a $20M Tech Micro-Cap
  4. Everyday Luxury, Unstoppable Scale: Aritzia Delivers 44% Net Revenue Growth
  5. Can Navy SEAL Leadership and Big Tech Scale Revolutionize Airborne Threat Detection?

Disclaimer


This report should not be viewed as investment advice or as an offer to buy or sell any securities or as an invitation or solicitation of an offer to buy or sell any securities. Neither the author of this report, its publisher, nor any other person associated with the publication of this report, are registered brokers, investment dealers, investment advisers, or financial advisers. The information in this report has not been tailored to the particular needs or circumstances of readers and should not be relied upon as investment advice or recommendations to purchase or sell any of the securities presented in this report. Readers seeking investment advice should contact qualified and registered brokers, investment dealers, investment advisers, or financial advisers prior to making any decision to buy or sell any of the securities referred to in this report. The information in this report should not be construed as investment, legal, or tax advice. No recommendation is made as to whether an investment in the presented securities is suitable for any reader in light of the reader’s particular circumstances.

Readers are cautioned that the publisher of this report covers exclusively securities that carry a high degree of volatility. Investing in such securities is highly speculative and carries a high degree of risk. Investors in such securities could lose all or a substantial portion of their investment. Only those investors who can afford to lose all or a substantial portion of their investment should consider investing in the securities referred to in this report.

This report may include information obtained from publicly available sources, including third-party reports or analysis. Neither the author nor publisher of this report, nor www.juniorstocks.com or its owners, have undertaken any independent investigation into the factual information used in this report, and the information in this report is provided without any warranty of any kind. No representations or warranties are provided regarding the accuracy or completeness of the information provided in this report. Statements of opinion or belief are those of the authors and/or publisher of this report. These statements of opinion or belief are expressions of the author’s and/or publisher’s judgment, and there is no guarantee that those judgments will turn out to be correct. No inference should be drawn that the author and/or publisher have any special or greater knowledge about the presented companies or their securities, or any particular expertise in the industries or markets in which the company operates. Readers should conduct their own due diligence and seek professional advice prior to investing in any securities presented on Juniorstocks.com.

Certain statements in this report constitute “forward-looking” statements. Forward-looking statements often, but not always, are identified by the use of words such as “seek,” “anticipate,” “believe,” “plan,” “estimate,” “expect,” “targeting,” and “intend” and statements that an event or result “may,” “will,” “should,” “could,” or “might” occur or be achieved and other similar expressions. Forward-looking statements express or involve discussions with respect to predictions, expectations, beliefs, plans, projections, objectives, goals, assumptions, or future events or performance; they are not statements of historical facts and should not be viewed as any guarantee of any future result. Forward-looking statements are based on expectations, estimates, and projections at the time the statements are made that involve a number of risks and uncertainties which could cause actual results or events to differ materially from those presently anticipated. The author and/or publisher of this report disclaims any obligation to update the forward-looking statements in this report, whether as a result of new information, future events, or results or otherwise. There is no assurance that forward-looking statements will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Accordingly, readers should not place undue reliance on forward-looking statements.

The information provided in this report is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to applicable law or regulation, or would subject the author or publisher of this report to any registration requirement in such jurisdiction or country.

Information about the editor of this publication:
Juniorstocks.com is a service provided by Piccadilly Capital Group, Office 66, 101 Clapham High Street, London, SW4 7TB, UK. Piccadilly Capital Group is not the publisher of this report and was not paid for the publication of this report. Piccadilly Capital Group seeks to generate web traffic and a growing number of followers through the publication of articles or reports. Directors, officers, and other insiders of the publisher own an interest in Piccadilly Capital Group. Piccadilly Capital Group does not endorse or recommend the business, products, services, or securities of any company mentioned on www.juniorstocks.com. Piccadilly Capital Group will not share your information with any outside third parties. Due to the new data protection basic regulation, we ask you to read our data protection declaration carefully.

Note on copyright:
The contents published on this website and on connected media (e.g., e-mail, X, Facebook) are subject to applicable copyright and ancillary copyright laws. Any use not permitted by applicable copyright and ancillary copyright laws requires the prior written consent of the provider or the respective rights holder. In particular, this applies to the duplication, editing, translation, storage, processing, or reproduction of content in databases or other electronic media and systems. Contents and rights of third parties are marked as such. Unauthorized reproduction or transmission of individual contents or complete pages is not permitted and is punishable by law. Only the production of copies and downloads for personal, private, and non-commercial use is permitted. Links to the provider's website are always welcome and do not require the consent of the provider of the website. Photos and images on the website may not be shared unless the publisher itself has acquired the initial rights from authorized sources. The presentation of this website in external frames is only allowed with written permission. If you notice any violations, please inform us. Please note: The content of our articles, emails, or other publications or social networks such as X, LinkedIn or Facebook is exclusively intended for the designated addressee(s). If you are not the addressee of these articles, emails, or other publications in the market letter or social networks such as Twitter or Facebook or his or her legal representative, please note that any form of publication, reproduction, or distribution of the content of these articles, emails, or other publications in the market letter or social networks such as X, LinkedIn or Facebook is prohibited. Falsifications of the original content of this message during data transmission cannot be excluded in principle.