SPONSORED

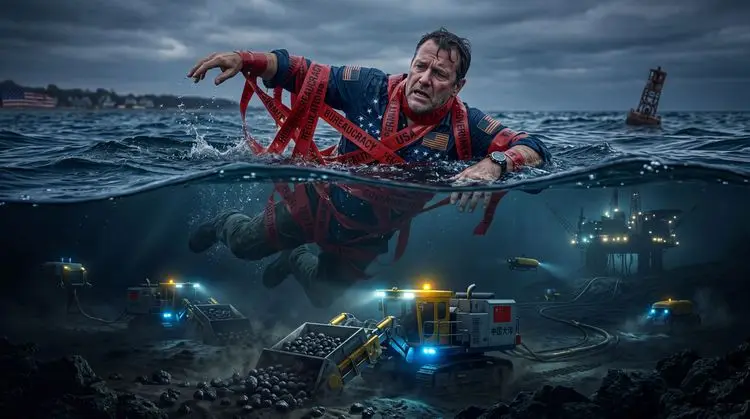
Drowning in Red Tape: While the West Debates Ethics, China Mines the Deep

How Beijing turned thirty years of Western regulatory hesitation into an uncontested industrial and military monopoly beneath the waves.
•• 1 Min
Drowning in Red Tape: While the West Debates Ethics, China Mines the Deep

While the West spent the last three decades learning how to swim in regulatory red tape and ethical hand-wringing over deep-sea mining, China was already deep-sea fishing for the future of global power.

Humanity has spent years looking up at the sky, mesmerized by the prospect of mining asteroids and colonizing Mars, while Beijing has been looking straight down to the bottom of the ocean.

This is not a traditional mining story; it is a masterclass in long-term strategic capability. The deep sea, comprising roughly half of the planet, remains largely unexplored and legally unclaimed, but the international race to dominate its resources is rapidly transforming these abyssal plains into the next major geopolitical flashpoint.

Under the watchful eye of the International Seabed Authority (ISA), the United Nations-affiliated body overseeing international waters, China has secured five exploration contracts. This is more than any other nation on Earth, covering polymetallic nodules, sulphides, and cobalt crusts. But the treasure hunt extends far beyond raw materials. Mining the deep ocean requires highly specialized robotics, heavy-duty submersibles, and advanced sonar systems, all of which possess distinct dual-use military capabilities. Security analysts note that China’s extensive oceanographic research fleet spends only a fraction of its time within designated mining zones. The vast majority of its operational hours are dedicated to mapping strategic maritime chokepoints and submarine transit corridors. By gathering precise bathymetric and acoustic data, state-backed entities are essentially constructing an underwater surveillance network. This data-driven landscape threatens to strip away the traditional stealth advantages enjoyed by Western naval forces, turning a resource play into a security stronghold.

The strategic encirclement does not stop in international waters. China has actively pursued bilateral partnerships in the South Pacific, striking co-exploration deals within the Exclusive Economic Zones of island nations like the Cook Islands and Kiribati. By embedding itself directly into the maritime backyards of regional powers, Beijing ensures its infrastructure is firmly anchored before the West can even agree on a rulebook. Western enterprises are waking up to this reality, but they are operating with a profound structural disadvantage. Private firms are bound by quarterly profit margins and intense public pressure over environmental degradation, whereas their Chinese state-backed counterparts enjoy multi-generational horizons insulated from electoral shifts.

Despite these hurdles, public-market players are pushing ahead. Leading the charge is The Metals Company (NASDAQ: TMC), which focuses on harvesting polymetallic nodules in the Clarion-Clipperton Zone of the Pacific. These potato-sized rocks are rich in nickel, cobalt, copper, and manganese—the exact cocktail required to fuel the clean energy transition and modern defense hardware. Similarly, European industrial heavyweights are anchoring their own claims. DEME Group NV (Euronext Brussels: DEME) operates extensively in seabed exploration through its specialized subsidiary, Global Sea Mineral Resources. In Scandinavia, innovators like Loke Marine Minerals have entered the fray by acquiring legacy seabed licenses previously held by Western defense conglomerates, looking to carve out a secure, non-Chinese supply chain for Europe.

The regulatory environment remains a chaotic maze, particularly for American interests. Because the United States has never ratified the UN Convention on the Law of the Sea, American companies lack a direct legal pathway to claim resources in international waters. To bypass this gridlock, firms are seeking alternative domestic frameworks. Recent regulatory milestones have seen companies navigate compliance determinations from the National Oceanic and Atmospheric Administration under legacy domestic statutes, providing a tentative baseline for Western operations. This includes exploratory tracking by micro-cap innovators like Deep Sea Minerals Corp. (CSE: SEAS) as they signal a renewed push for Western mineral independence.

The rush to vacuum up the ocean floor is fundamentally about maintaining a broader industrial monopoly. China already controls approximately 60% of terrestrial critical mineral production and a staggering 85% of global processing capacity. For Beijing, seabed extraction is a preventative measure designed to ensure that even if the global supply chain shifts from land to sea, the world will still rely on Chinese refining infrastructure. Terrestrial giants like China Rare Earth Resources and Technology Co., Ltd. (Shenzhen Stock Exchange: 000831.SZ) are heavily integrated into this vertical ecosystem. By expanding state influence into marine environments, these mega-corporations can effectively hedge against land-based resource depletion while ensuring Western competitors remain structurally dependent.

Ultimately, the deep-sea race is not just about who plants the first flag on the seabed.

It is about who owns the proprietary technology, who compiles the topographic data, and who dictates the international maritime standards. As Western policymakers face the choice between enforcing strict environmental moratoriums and countering a supply chain monopoly, the window to contest the ocean floor is rapidly closing.

Sources:

  • International Seabed Authority (ISA) documentation on global exploration contracts and seabed mining regulations.
  • National Oceanic and Atmospheric Administration (NOAA) regulatory compliance frameworks under the Deep Seabed Hard Mineral Resources Act.
  • Mongabay Data Studio and CNN International Investigation fleet tracking data and operational analysis of Chinese oceanographic research vessels.
  • RAND Corporation strategic reports detailing critical mineral supply chain security and terrestrial processing monopolies.
  • Financial data, market tracking, and corporate disclosures for The Metals Company, DEME Group NV, Deep Sea Minerals Corp., and China Rare Earth Resources and Technology Co., Ltd.

Most Popular News

  1. SpaceX’s $8B Spectrum Deal Sends AT&T, Verizon, and T-Mobile Plummeting
  2. Is Project Vault Securing America’s Supply Chain or Squeezing It to the Breaking Point?
  3. Why Gautam Lohia Shifted from Global Consulting to Reboot a $20M Tech Micro-Cap
  4. Everyday Luxury, Unstoppable Scale: Aritzia Delivers 44% Net Revenue Growth
  5. Can Navy SEAL Leadership and Big Tech Scale Revolutionize Airborne Threat Detection?

Disclaimer


This report should not be viewed as investment advice or as an offer to buy or sell any securities or as an invitation or solicitation of an offer to buy or sell any securities. Neither the author of this report, its publisher, nor any other person associated with the publication of this report, are registered brokers, investment dealers, investment advisers, or financial advisers. The information in this report has not been tailored to the particular needs or circumstances of readers and should not be relied upon as investment advice or recommendations to purchase or sell any of the securities presented in this report. Readers seeking investment advice should contact qualified and registered brokers, investment dealers, investment advisers, or financial advisers prior to making any decision to buy or sell any of the securities referred to in this report. The information in this report should not be construed as investment, legal, or tax advice. No recommendation is made as to whether an investment in the presented securities is suitable for any reader in light of the reader’s particular circumstances.

Readers are cautioned that the publisher of this report covers exclusively securities that carry a high degree of volatility. Investing in such securities is highly speculative and carries a high degree of risk. Investors in such securities could lose all or a substantial portion of their investment. Only those investors who can afford to lose all or a substantial portion of their investment should consider investing in the securities referred to in this report.

This report may include information obtained from publicly available sources, including third-party reports or analysis. Neither the author nor publisher of this report, nor www.juniorstocks.com or its owners, have undertaken any independent investigation into the factual information used in this report, and the information in this report is provided without any warranty of any kind. No representations or warranties are provided regarding the accuracy or completeness of the information provided in this report. Statements of opinion or belief are those of the authors and/or publisher of this report. These statements of opinion or belief are expressions of the author’s and/or publisher’s judgment, and there is no guarantee that those judgments will turn out to be correct. No inference should be drawn that the author and/or publisher have any special or greater knowledge about the presented companies or their securities, or any particular expertise in the industries or markets in which the company operates. Readers should conduct their own due diligence and seek professional advice prior to investing in any securities presented on Juniorstocks.com.

Certain statements in this report constitute “forward-looking” statements. Forward-looking statements often, but not always, are identified by the use of words such as “seek,” “anticipate,” “believe,” “plan,” “estimate,” “expect,” “targeting,” and “intend” and statements that an event or result “may,” “will,” “should,” “could,” or “might” occur or be achieved and other similar expressions. Forward-looking statements express or involve discussions with respect to predictions, expectations, beliefs, plans, projections, objectives, goals, assumptions, or future events or performance; they are not statements of historical facts and should not be viewed as any guarantee of any future result. Forward-looking statements are based on expectations, estimates, and projections at the time the statements are made that involve a number of risks and uncertainties which could cause actual results or events to differ materially from those presently anticipated. The author and/or publisher of this report disclaims any obligation to update the forward-looking statements in this report, whether as a result of new information, future events, or results or otherwise. There is no assurance that forward-looking statements will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Accordingly, readers should not place undue reliance on forward-looking statements.

The information provided in this report is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to applicable law or regulation, or would subject the author or publisher of this report to any registration requirement in such jurisdiction or country.

Information about the editor of this publication:
Juniorstocks.com is a service provided by Piccadilly Capital Group, Office 66, 101 Clapham High Street, London, SW4 7TB, UK. Piccadilly Capital Group is not the publisher of this report and was not paid for the publication of this report. Piccadilly Capital Group seeks to generate web traffic and a growing number of followers through the publication of articles or reports. Directors, officers, and other insiders of the publisher own an interest in Piccadilly Capital Group. Piccadilly Capital Group does not endorse or recommend the business, products, services, or securities of any company mentioned on www.juniorstocks.com. Piccadilly Capital Group will not share your information with any outside third parties. Due to the new data protection basic regulation, we ask you to read our data protection declaration carefully.

Note on copyright:
The contents published on this website and on connected media (e.g., e-mail, X, Facebook) are subject to applicable copyright and ancillary copyright laws. Any use not permitted by applicable copyright and ancillary copyright laws requires the prior written consent of the provider or the respective rights holder. In particular, this applies to the duplication, editing, translation, storage, processing, or reproduction of content in databases or other electronic media and systems. Contents and rights of third parties are marked as such. Unauthorized reproduction or transmission of individual contents or complete pages is not permitted and is punishable by law. Only the production of copies and downloads for personal, private, and non-commercial use is permitted. Links to the provider's website are always welcome and do not require the consent of the provider of the website. Photos and images on the website may not be shared unless the publisher itself has acquired the initial rights from authorized sources. The presentation of this website in external frames is only allowed with written permission. If you notice any violations, please inform us. Please note: The content of our articles, emails, or other publications or social networks such as X, LinkedIn or Facebook is exclusively intended for the designated addressee(s). If you are not the addressee of these articles, emails, or other publications in the market letter or social networks such as Twitter or Facebook or his or her legal representative, please note that any form of publication, reproduction, or distribution of the content of these articles, emails, or other publications in the market letter or social networks such as X, LinkedIn or Facebook is prohibited. Falsifications of the original content of this message during data transmission cannot be excluded in principle.