SPONSORED

China wants to increase coal production and increase electricity prices

Country is grappling with the worst energy crisis in years.
•• 6 Min
China wants to increase coal production and increase electricity prices

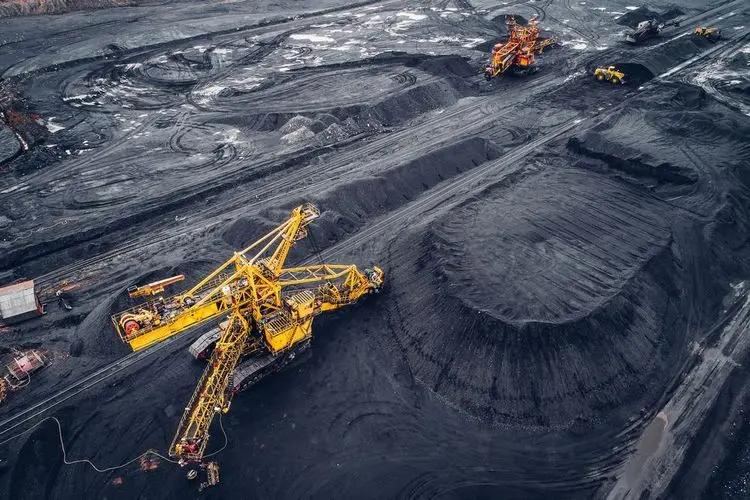
China has instructed its two most important coal regions to increase production, and will allow the coal-fired power plants to calculate customers higher prices as the country has been fighting for years with the worst energy crisis.

Inner Mongolia and Shanxi had the coal mines to increase their annual production capacity by a total of more than 160 million tonnes, while the Chinese Cabinet declared that electricity prices for coal-fired power plants may now deviate by up to 20% of the base rates, which is an increase in represents previous upper limits, and more for sectors with high energy consumption.

The price adjustment should prevent high energy consumption, the state media reported and added that prices for private households and agricultural users as well as for the initiatives to promote the common good are to be kept stable.

Almost record-related high prices for power plant coal and electricity bottlenecks that have led to electricity rations throughout China have impaired industrial production of the country and threaten economic growth.

Shanxi, China's largest coal-producing region, has instructed its 98 coal mines to increase the annual funding capacity for the rest of the year by 55.3 million tonnes, such as a provincial government official confirmed on Friday in a document covered by Reuters.

Shanxi also will allow 51 coal mines, which had reached its maximum annual production, to further produce in the fourth quarter and to increase capacity by 8 million tons, which may lead to an additional range of 20.65 million tonnes.

In China's second largest coal region, the internal Mongolia, the local authorities were invited in an urgency release of 7 October from 7 October from the Energy Department of the region to notify 72 mines that they can now work with the prescribed higher capacity, provided that they ensure safe production .

An official of the Ministry refused to say how long the production increase would take.

The announcement was followed after a meeting in which regional authorities had developed measures for energy supply in winter on the directive of the Chinese Cabinet, the so-called State Council, as the Inner Mongolia Daily reported on Friday.

"Government's coal-task force is intended to push the miners to increase production uncompromisingly, while the energy-task force should bring the power generators to guarantee the coverage of electricity and heat demand in winter," says the newspaper .

"This shows that the government is serious with the increase in local coal production to relieve the scarcity," said a Beijing-based dealer, who appreciated that it could take two to three months until the increase in production occurs.

The 72 mines in the internal Mongolia, which are largely a tape, had so far an approved annual capacity of 178.45 million tonnes.

The announcement is proposed to increase these by 98.35 million tonnes, such as Reuters calculations revealed.

"This will help to alleviate the coal scarcity, but can not eliminate the problem," said Lara Dong, Senior Director at IHS Markit. "The government will still need to make electricity rations to ensure the balance of coal and current markets over the winter."

The appointment contracts for Chinese power plant coal from Zhengzhou were traded in the night session on Friday by 1347 GMT with a plus of 2.2% at around 1,333 yuan ($ 207) per tonne and were thus not far from a record high of 1.408 yuan, the end last month has been reached.

The prices for other power generating raw materials are also climbed in height, including fuel oil, methanol and LPG (LPG). They all have risen by at least 10% compared to the previous month, as the power generators are hinging to fuel.

Increase in imports

According to official data, inner Mongolia produced slightly more than 1 billion tons in 2020, which corresponds more than a quarter of national overall production.

However, production decreased by 8% in 2020 and dropped every month from April to July of this year, which is partly due to a Beijing's anti-corruption examination in the coal sector in the last year, which led to a smaller production, as miners was prohibited to produce beyond the authorized capacity.

The neighboring province of Shanxi had to close 27 coal mines this week for floods. Coal supplies in the Great Chinese ports amounted to 52.4 million tonnes at the end of September before one-week National Day, which began on October 1, and were thus 18% below the previous year's level, such as Data of China Coal Transportation and Distribution Association.

In order to ensure the electricity and heat supply of private households, China has reopened dozens of other mines and approved several new ones.

The government has also called on to raise the carbon imports "adequate" to the level of last year after imports declined by almost 10% in the first eight months.

Despite an almost one-year unofficial import ban, it has even released Australian coal from intermediate storage, and the utilities tapped rare sources such as Kazakhstan and the United States.

Meanwhile, coal consumption in the northeast of China increases in winter at the beginning of the heating season, with the large power plants on average inventories for about 10 days, while there were more than 20 days last year.

Economic pressure

Citi predicted that the bottleneck stopped and China would force to reduce the electricity consumption of the industry in the fourth quarter by 12% - in the case of a cold winter even more.

"This would increase the stagflation risks and growth pressure on the Chinese and global economy in the coming winter," wrote Citi analysts in a note.

Despite the announced increase in production in Shanxi and inner Mongolia, according to analysts and dealers, not much for this winter will be expected.

The analysts of Guosheng Securities assume that China's lack of power plant coal will exceed 2021 116 million tonnes, although from the fourth quarter, 31 million tonnes of newly authorized capacities are put into operation.

"We expect further announcements to increase coal production," said James Stevenson, coal analyst at the consulting firm IHS Markit, and added that China has used all its most important instruments to increase the domestic offer and demand steer.

The benchmark spot prices for power plant coal in the northern harbor of Qinhuangdao reached a record high of 1,079 yuan per ton at the end of September.

With the rising coal prices, more and more power plants slide into the red numbers and even stand in front of the closure.

"Much more people and companies had sat in the dark when China built only coal-fired power plants and did not expand solar and wind power capacities," says Lauri Myllyvirta, senior analyst at the Center for Research on Energy and Clean Air.

(1 $ = 6,4507 Chinese yuan)

ChinaCoalElectricity

Most Popular News

  1. SpaceX’s $8B Spectrum Deal Sends AT&T, Verizon, and T-Mobile Plummeting
  2. Is Project Vault Securing America’s Supply Chain or Squeezing It to the Breaking Point?
  3. Why Gautam Lohia Shifted from Global Consulting to Reboot a $20M Tech Micro-Cap
  4. Everyday Luxury, Unstoppable Scale: Aritzia Delivers 44% Net Revenue Growth
  5. Can Navy SEAL Leadership and Big Tech Scale Revolutionize Airborne Threat Detection?

Disclaimer


This report should not be viewed as investment advice or as an offer to buy or sell any securities or as an invitation or solicitation of an offer to buy or sell any securities. Neither the author of this report, its publisher, nor any other person associated with the publication of this report, are registered brokers, investment dealers, investment advisers, or financial advisers. The information in this report has not been tailored to the particular needs or circumstances of readers and should not be relied upon as investment advice or recommendations to purchase or sell any of the securities presented in this report. Readers seeking investment advice should contact qualified and registered brokers, investment dealers, investment advisers, or financial advisers prior to making any decision to buy or sell any of the securities referred to in this report. The information in this report should not be construed as investment, legal, or tax advice. No recommendation is made as to whether an investment in the presented securities is suitable for any reader in light of the reader’s particular circumstances.

Readers are cautioned that the publisher of this report covers exclusively securities that carry a high degree of volatility. Investing in such securities is highly speculative and carries a high degree of risk. Investors in such securities could lose all or a substantial portion of their investment. Only those investors who can afford to lose all or a substantial portion of their investment should consider investing in the securities referred to in this report.

This report may include information obtained from publicly available sources, including third-party reports or analysis. Neither the author nor publisher of this report, nor www.juniorstocks.com or its owners, have undertaken any independent investigation into the factual information used in this report, and the information in this report is provided without any warranty of any kind. No representations or warranties are provided regarding the accuracy or completeness of the information provided in this report. Statements of opinion or belief are those of the authors and/or publisher of this report. These statements of opinion or belief are expressions of the author’s and/or publisher’s judgment, and there is no guarantee that those judgments will turn out to be correct. No inference should be drawn that the author and/or publisher have any special or greater knowledge about the presented companies or their securities, or any particular expertise in the industries or markets in which the company operates. Readers should conduct their own due diligence and seek professional advice prior to investing in any securities presented on Juniorstocks.com.

Certain statements in this report constitute “forward-looking” statements. Forward-looking statements often, but not always, are identified by the use of words such as “seek,” “anticipate,” “believe,” “plan,” “estimate,” “expect,” “targeting,” and “intend” and statements that an event or result “may,” “will,” “should,” “could,” or “might” occur or be achieved and other similar expressions. Forward-looking statements express or involve discussions with respect to predictions, expectations, beliefs, plans, projections, objectives, goals, assumptions, or future events or performance; they are not statements of historical facts and should not be viewed as any guarantee of any future result. Forward-looking statements are based on expectations, estimates, and projections at the time the statements are made that involve a number of risks and uncertainties which could cause actual results or events to differ materially from those presently anticipated. The author and/or publisher of this report disclaims any obligation to update the forward-looking statements in this report, whether as a result of new information, future events, or results or otherwise. There is no assurance that forward-looking statements will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Accordingly, readers should not place undue reliance on forward-looking statements.

The information provided in this report is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to applicable law or regulation, or would subject the author or publisher of this report to any registration requirement in such jurisdiction or country.

Information about the editor of this publication:
Juniorstocks.com is a service provided by Piccadilly Capital Group, Office 66, 101 Clapham High Street, London, SW4 7TB, UK. Piccadilly Capital Group is not the publisher of this report and was not paid for the publication of this report. Piccadilly Capital Group seeks to generate web traffic and a growing number of followers through the publication of articles or reports. Directors, officers, and other insiders of the publisher own an interest in Piccadilly Capital Group. Piccadilly Capital Group does not endorse or recommend the business, products, services, or securities of any company mentioned on www.juniorstocks.com. Piccadilly Capital Group will not share your information with any outside third parties. Due to the new data protection basic regulation, we ask you to read our data protection declaration carefully.

Note on copyright:
The contents published on this website and on connected media (e.g., e-mail, X, Facebook) are subject to applicable copyright and ancillary copyright laws. Any use not permitted by applicable copyright and ancillary copyright laws requires the prior written consent of the provider or the respective rights holder. In particular, this applies to the duplication, editing, translation, storage, processing, or reproduction of content in databases or other electronic media and systems. Contents and rights of third parties are marked as such. Unauthorized reproduction or transmission of individual contents or complete pages is not permitted and is punishable by law. Only the production of copies and downloads for personal, private, and non-commercial use is permitted. Links to the provider's website are always welcome and do not require the consent of the provider of the website. Photos and images on the website may not be shared unless the publisher itself has acquired the initial rights from authorized sources. The presentation of this website in external frames is only allowed with written permission. If you notice any violations, please inform us. Please note: The content of our articles, emails, or other publications or social networks such as X, LinkedIn or Facebook is exclusively intended for the designated addressee(s). If you are not the addressee of these articles, emails, or other publications in the market letter or social networks such as Twitter or Facebook or his or her legal representative, please note that any form of publication, reproduction, or distribution of the content of these articles, emails, or other publications in the market letter or social networks such as X, LinkedIn or Facebook is prohibited. Falsifications of the original content of this message during data transmission cannot be excluded in principle.